
Ten years of mortgages, one dedicated broker.

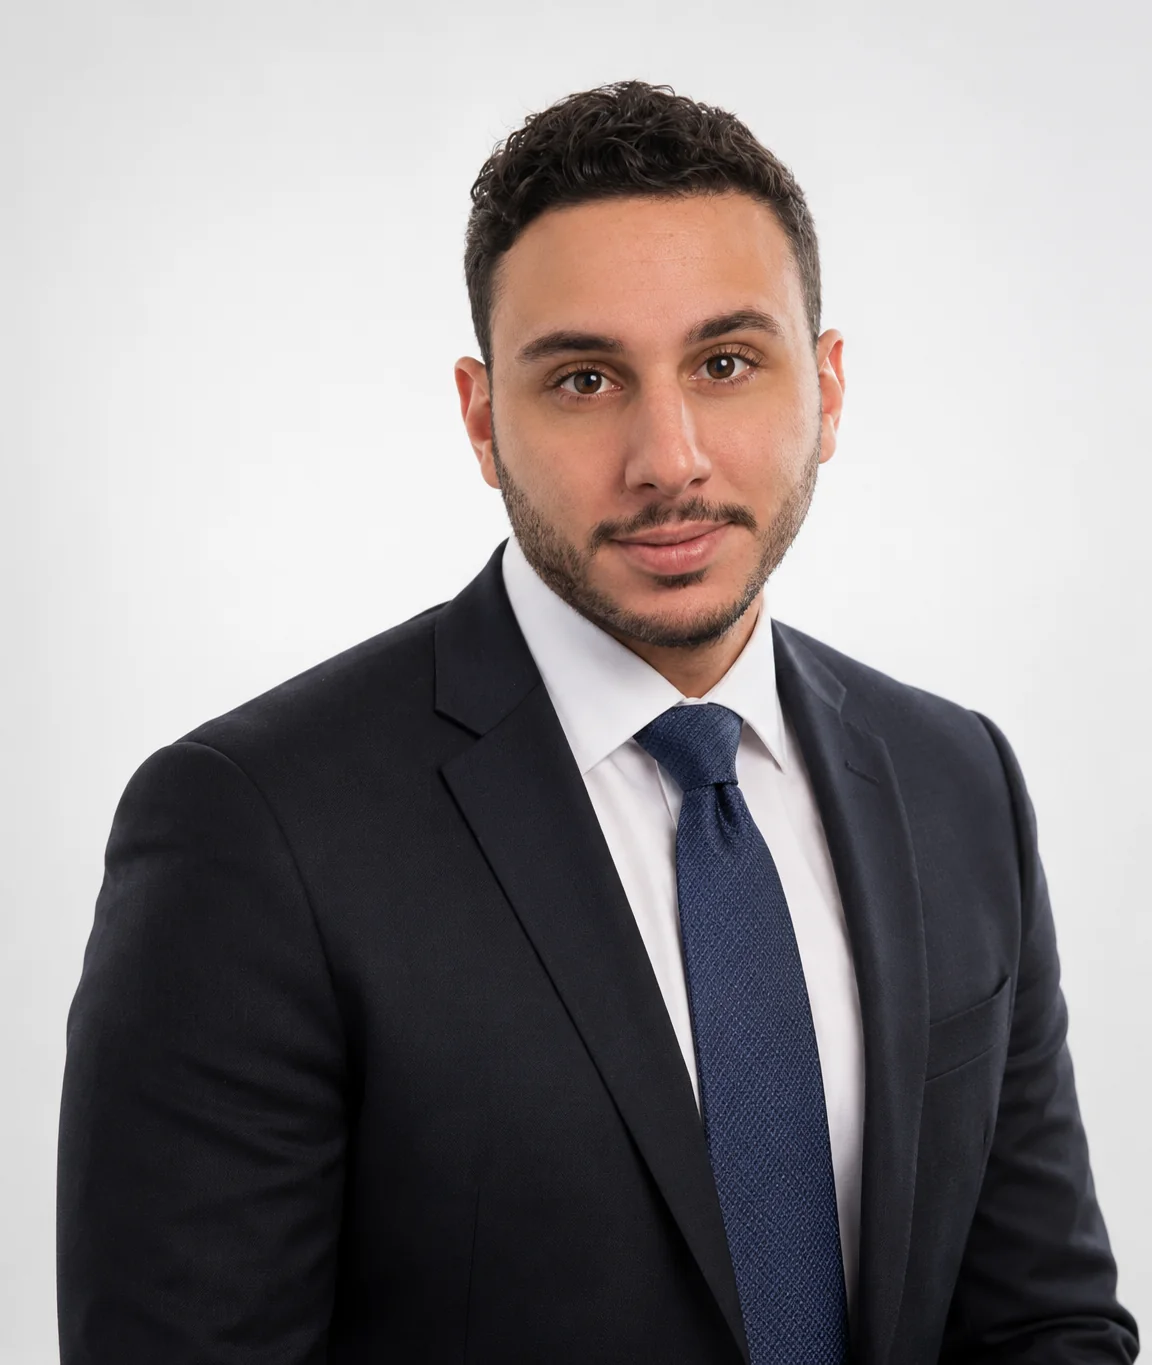
Frederick Amar · Licensed Mortgage Broker, Quebec

Frederick Amar supports buyers, refinancers and renewing homeowners in Quebec. His more than ten years of experience and personalized approach keep your project at the centre of the conversation.

A note from Frederick

Who is Frederick Amar?

I have worked in mortgages for more than ten years. I built my practice on a simple idea: a mortgage is often the biggest financial commitment a family makes, so it deserves a real person who follows the file from the first call to the day the funds are released.

What drew me to this field is that it is both technical and deeply personal. A quarter-point difference in the rate changes a household's monthly budget. A prepayment penalty that nobody explained can wipe out months of savings. And a renewal signed without comparing options can cost much more than necessary over the term.

Over the years, I have worked with first-time buyers looking for a condo in Laval, families moving to a bigger home outside Montreal, homeowners refinancing to consolidate debt or renovate, and long-time clients renewing for the second or third time. Some files are more complex than others, but the goal stays the same: a mortgage plan you understand, with terms compared across many lenders, not just one bank.

My role is to help you compare your options and to guide you through every step of your mortgage project.

— Frederick Amar Mortgage Broker · Quebec, Canada

Guiding principles

What does “client-first” actually mean in Frederick's practice?

Client-first isn't a slogan on a lender's brochure. It shows up in small, testable behaviours: who returns your call, whether the numbers on paper match the numbers you were told, and whether anyone is still there when your renewal comes around three or five years later. Below is what to expect.

  • One dedicated broker, start to finish Your file is not passed to a call-centre queue. Frederick answers his phone, and his team steps in when timing is tight.
  • Real rate shopping, not a single-lender pitch Frederick compares options from banks, credit unions and other mortgage lenders.
  • Plain-language explanations before signature Prepayment privileges, penalties, portability, and rate holds are explained in plain language before you sign anything.
  • Service in French or English Bilingual conversations, bilingual documents, and clear explanations of every clause and cost in whichever language you prefer.
  • Digital on your schedule, not the bank's The entire process can be completed remotely.
  • The relationship continues past funding Frederick stays on for renewals, refinances, and the occasional “what if we sell and buy” conversation years down the line.

Frederick Amar's awards

Ratehub Top Performer: 2021, 2022, 2023, 2024 and 2025.

The client-first commitment

How does Frederick keep every conversation independent?

The short answer: for a standard residential mortgage, Frederick is compensated by the lender when your mortgage closes, not by you. That structure only works if the recommendation is honestly the best one for the file: a client who feels sold refinances or renews elsewhere, and the relationship ends.

The lender pool is the whole market

Frederick pulls live pricing from major Canadian banks, credit unions, and monoline lenders through the lender marketplace. You see the field before you pick, so your choice comes from a real comparison, not from being cornered.

Numbers before narratives

Fixed versus variable, five-year versus three-year, insured versus uninsured: each option is walked through with real dollar figures tied to your file, so the recommendation stands or falls on the math.

No product bundling pressure

Frederick never pushes extra products to win your file. Some lenders do require an account with them as a condition of their mortgage; when that is the case, Frederick tells you upfront so you can factor it into your comparison.

Explore how this looks day to day in Frederick's mortgage services, or read verbatim client accounts on the reviews page.

About Frederick · FAQ

About Frederick: frequently asked questions

Questions clients tend to ask before the first phone call, not about the mortgage process itself, but about who Frederick is and how his practice is set up. As of 2026, the answers below reflect how his practice is set up in Quebec.

How long has Frederick been advising Quebec borrowers?

Frederick has been active in Canadian mortgages for more than ten years and has worked with thousands of clients across purchases, refinances, renewals, and transfers. That decade covers several full rate cycles, which is one of the reasons his advice on fixed versus variable is grounded in observed behaviour rather than a single market moment.

Does Frederick work in French and English?

Yes. Every conversation, document review and lender explanation is available in French or in English, whichever you prefer. Frederick and his team work in your language from start to finish, so nothing gets lost in translation, from prepayment penalties to closing-day paperwork.

Who else is on Frederick's team?

Frederick is supported by his team, including his assistant Suzanne, who helps clients through their mortgage application and communication with lenders.

Why work with Frederick rather than a bank branch?

A branch officer can only offer their own institution's mortgage products at the rates their employer sets. Frederick shops the same file across Big Six banks, credit unions, and monoline lenders through the lender marketplace, and he owns the file end-to-end: a single point of contact rather than a queue that reassigns you between renewals.

How does Frederick find the right option for my file?

Frederick compares the available options for your file. Contact him for information relevant to your project.

Ready to talk it through?

A 15-minute conversation, no pitch attached.

The best way to know whether Frederick is the right broker for your file is a short call. Bring your goals, your timeline, and whatever mortgage paperwork is already in front of you. Frederick will listen first, then map out what a personalized rate quote would look like, no obligation, no cost.